Definition of C-Corp and S-Corp
Both C-Corps and S-Corps are corporations. Before going into the details of each, let's understand what a corporation is.What is a corporation
is an American business entity created by filing articles of incorporation with a secretary of state. The owners of a corporation are shareholders, and they elect a board of directors to make decisions on behalf of the company. In addition, a corporation can issue shares to raise capital and, in some cases, can be publicly traded. Corporations also offer limited liability: shareholders are not personally liable for the corporation's debts. However, unlike other business structures, corporations must comply with legal requirements and corporate formalities in order to operate properly.What is a C-Corp
C-Corp status is the tax structure the IRS applies to a corporation by default. The main characteristic of C-Corps is that they are subject to double taxation: first they pay corporate taxes, and then shareholders must pay personal taxes on the gains from dividends or the sale of shares. The main reason to be taxed as a C-corp is that, unlike S-Corps, there are no restrictions on who can own shares, nor a limit on the total number of shareholders.What is an S-Corp
is not subject to double taxation. The IRS treats them as pass-through entities, so they don't pay corporate taxes and taxes are only collected on their shareholders' income. However, to qualify as an S-Corp, that:- It cannot have more than 100 shareholders
- It must issue only one class of stock
- Ownership is limited to American individuals, certain trusts, and nonprofit organizations.
- It must not be an ineligible corporation
- It must be a domestic corporation
C-Corp vs S-Corp: Comparison
Now that we have defined both tax structures, let's put them side by side and compare them to help you decide more easily which one fits your business.| Features | C-Corp | S-Corp |
|---|---|---|
| Formation | Articles of Incorporation (C-corp is the default tax structure for corporations) | Articles of Incorporation + IRS Form 2553. |
| Taxes | Double taxation: corporate income and personal income | Only one tax, on personal income |
| Loss deductions | Cannot be deducted on personal tax returns | Can be deducted on personal tax returns |
| Tax filing | Every 3 months | Once a year |
| Number of Shareholders | Unlimited | Maximum of 100 |
| Type of Shareholders | All eligible entities | Individuals and certain estates, trusts, tax-exempt organizations |
| Shareholder Origin | No restrictions | US citizens or permanent residents |
| Classes of Stock | No restrictions | Only one class of stock can be issued |
| IRS Scrutiny | Normal | Above average regarding the balance of salary vs. dividends |
| Equity Financing | Easier to raise capital | Harder to raise capital |
Similarities between C-Corps and S-Corps
If we compare both structures, we'll find several similarities between them.Personal liability protection
State laws establish that corporations are legal entities separate from their owners. This means that shareholders are not personally liable for the company's debts, and their personal assets are protected from potential creditor claims.Structure
In both types of corporations, shareholders elect directors to oversee the day-to-day operations of the business. As the corporation generates profits, dividends are distributed to shareholders based on the number of shares they own.Legal obligations
To remain compliant, both C-Corps and S-Corps must:- Issue shares
- Adopt bylaws
- Hold annual meetings of directors and shareholders
- Keep meeting minutes
- Issue written corporate resolutions for major decisions
- File annual reports with the state government
- Pay annual fees
Differences between C-Corps and S-Corps
Formation
When the Articles of Incorporation are filed with the secretary of state, corporations begin their existence as C corporations. They become S corporations by filing IRS Form 2553. To obtain S corp status for a given year, Form 2553 must be filed by March 15 if the corporation operates on a calendar year. Corporations operating on a different fiscal year can file it by the 15th day of the third month of the fiscal year.Taxation
The main reason to choose S corp status is to save on taxes. As we mentioned, C-Corps are subject to double taxation: they must pay corporate taxes on their profits and then shareholders pay taxes again on what they receive as dividends. Electing S corp status makes it possible to avoid double taxation. C corporations file taxes using Form 1120, while S corporations file Form 1120-S.Ownership
The main advantage of C-Corps is that they offer greater flexibility in selling shares. Unlike S-Corps, C-Corps have no limits on the number of shareholders, their nationality or citizenship, or the classes of stock they can issue. This makes it easier for them to grow and raise investment.Deductions for shareholder benefits
C-Corps can deduct business benefits provided to shareholders who are also employees (life insurance, disability, etc.). These are not taxable to the shareholder, as long as the benefits are extended to at least 70% of employees. An S corporation, on the other hand, cannot do this, and these benefits become taxable for a shareholder who owns more than 2% of the shares.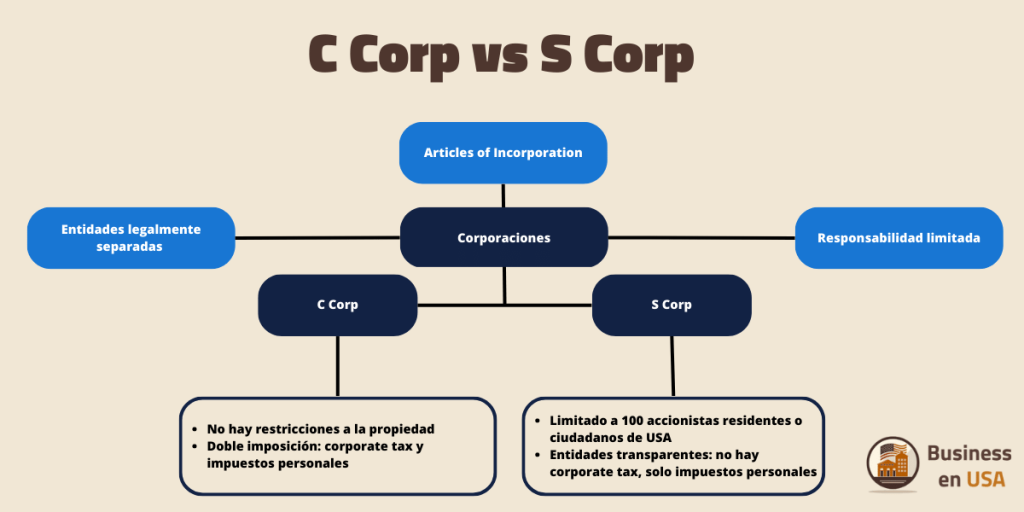
Should I choose C-Corp or S-Corp status?
There is no one-size-fits-all answer to this question; it will depend on the situation of each business owner and their company.When might a C-Corp be preferable?
Business owners usually choose to open a C-Corp when the following conditions are met:- C-Corp taxation would result in lower taxes than being taxed as an S-Corp.
- No large dividend distributions will be made to shareholders, which reduces the double taxation problem.
- You plan to go public (IPO) and raise investment easily, without any restriction on who can invest in the company.
- You want shares to be freely and easily transferable.
- You want to issue different classes of stock.
When might an S-Corp be preferable?
Opening an S-Corp is usually preferred when:- You have no plans to take your company public, you don't intend to have more than 100 shareholders, and you don't want types of investors that are not allowed under Subchapter S.
- The corporation will distribute its income to shareholders.
- You have no plans to issue preferred stock. Having a single class of stock for all members is not a problem.
- The shareholders' tax liability, considering their personal income tax rate, deductions and exemptions, will be lower using a pass-through entity than an entity taxed separately.
Conclusion
Deciding between opening an S-Corp or a C-Corp is not obvious, especially when it's very hard to know what situation your company will be in 10 or 20 years from now... In addition, tax matters can vary greatly depending on each person's situation. That's why, at Business en USA, we always recommend getting our legal and financial advice before making any kind of decision. Finally, it's important to note that if you choose the S-Corp tax structure, you can go back. You only need to file a written statement with the IRS, along with consent signed by the majority of your corporation's shareholders. Get professional help to open your Corp- US business experts
- Legal and accounting team
- Free first consultation
Get your questions answered now

Written by
Ignacio Navarro
Ignacio Navarro is a Certified Public Accountant, founder of Start Companies and a specialist in U.S. companies for entrepreneurs, freelancers and digital businesses in Latin America. With training in international taxation and studies at UCEMA, he advises non-resident clients on forming and maintaining LLCs, opening bank accounts, invoicing, accounting and taxes. His experience combines tax strategy, compliance and practical vision for operating in the U.S. in a simple, organized and professional way.